

This is for informational purposes only and does not constitute investment advice. The author holds no position in BMNR. All data sourced from SEC filings, company press releases, and public market data as of 17 April 2026.
TL;DR
BMNR’s weekly ETH buying pace collapsed ~75% in January 2026, and ETH fell 35% in the weeks that followed
The executive chairman’s compensation is tied to total ETH accumulated, not ETH per share — meaning he benefits from diluting minority shareholders
At 0.96× NAV with the capital-markets channel effectively closed, BMNR offers ETH exposure with three extra risks attached and no compensating premium
Between July 2025 and December 2025, a single company spent up to $600 million per week buying Ethereum. Then it stopped. In the weeks that followed, ETH fell 35%. This piece asks whether that was a coincidence — and what it means for the $12 billion stock built on top of that ETH stack.
The company is Bitmine Immersion Technologies (NYSE: BMNR). You may not have heard of it. By dollar volume it is currently one of the most actively traded stocks on the US market. And it raises one of the more interesting questions in crypto markets right now: what happens to an asset when its biggest buyer steps back?
What is BMNR?
Bitmine started life as a small Las Vegas-based Bitcoin mining and hosting company. In June 2025, new executive chairman Thomas Lee — better known as the perma-bull head of research at Fundstrat — pivoted the company entirely. The new strategy: become the world’s largest listed Ethereum treasury company, explicitly modelling the approach on Michael Saylor’s playbook at MicroStrategy, but applied to ETH instead of BTC.
The pivot was seeded by a $250 million PIPE from Founders Fund, Pantera, Galaxy Digital, Kraken, and others. Subsequent share issuances — executed while BMNR traded at a large premium to the value of its ETH holdings — funded an aggressive accumulation program. By April 2026, BMNR held 4.87 million ETH tokens, representing 4.04% of total ETH supply. The stated target is 5%.
Two things sit alongside the treasury. First, MAVAN (Made in America Validator Network), a staking platform launched in March 2026 that currently stakes ~3.33 million of the company’s own ETH and is positioned as a future institutional staking service. Second, minority equity stakes in two private companies — Beast Industries and Eightco Holdings — intended to provide non-ETH optionality.
Why anyone owns this stock
Before explaining why we’re cautious, it’s worth being honest about the bull case. BMNR offers three things that are genuinely hard to replicate elsewhere:
Leveraged ETH exposure in a regulated US wrapper. For institutional mandates restricted to listed equities or retail investors who prefer not to self-custody, BMNR provides ETH beta with NYSE transparency and standard tax treatment. Its historical beta to ETH has run at 2-3× during rallies — materially above what spot ETH ETFs deliver.
Staking yield accrual. Unlike spot ETH or ETH ETFs, BMNR stakes its holdings and captures the ~2.8% annual staking yield. At full deployment this is a ~$280M annual revenue stream with high operating leverage.
MAVAN optionality. If the staking platform successfully wins third-party institutional mandates, it becomes a scalable fee business — a genuine call option that isn’t captured in the treasury NAV.
Each of these is real. Here is why we think they are outweighed.
The marginal-buyer problem
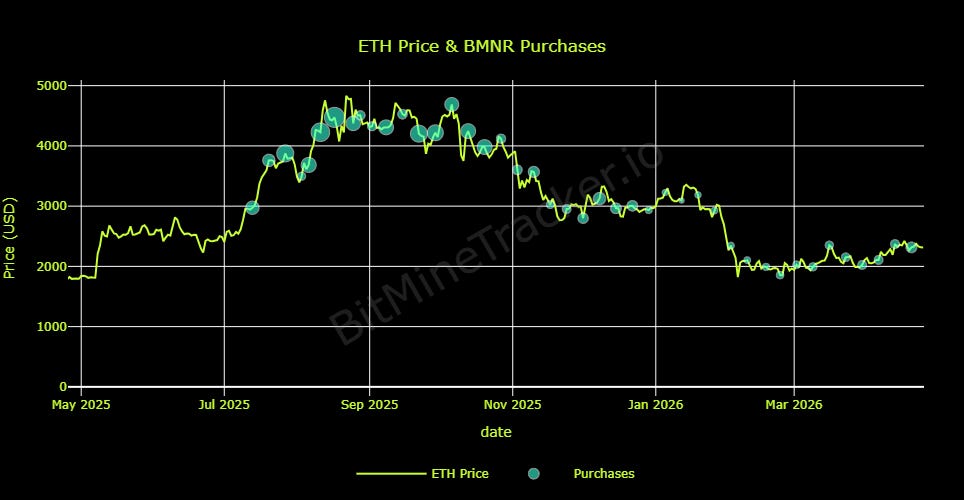
BMNR spent up to ~$600M per week buying ETH in August–September 2025. When its buying pace collapsed ~75% in January 2026, ETH fell 35% in the weeks that followed.
This is the chart that matters most. Each bubble represents a week of BMNR’s ETH purchases, sized by the number of tokens bought. What it shows:
From July to September 2025, BMNR was buying at a pace of $400–600M per week. Over the same period, ETH rose from ~$2,600 to ~$4,300 — close to its all-time high.
Buying peaked on the week ending 22 December 2025: 98,852 ETH acquired at ~$2,991 per token, roughly $300M in a single week.
In January 2026, the buying pace collapsed to approximately $70M per week — a 75% reduction. ETH fell from $2,991 to a trough near $2,100.
We are not claiming BMNR was solely responsible for ETH’s price level. But the data is consistent with a specific dynamic: BMNR was providing a large and consistent bid into the ETH spot market, and pre-existing holders were using that bid as an exit. When the bid stepped back, there was insufficient alternative demand to hold the price level.
This matters for BMNR investors because the company’s average cost basis is approximately $2,850–$2,950 per ETH. At a current ETH spot of $2,358, the treasury sits on roughly $2.4–2.9 billion of unrealized losses. The virtuous cycle — issue shares at a premium, buy ETH, ETH rises, shares trade higher, issue more shares — works in reverse when the premium disappears. And the premium has now disappeared.
The cost of capital trap
BMNR’s closest peer is Strategy Inc. (MSTR), which has built a $94B market cap on a BTC treasury. MSTR still trades at a 21% premium to the value of its crypto holdings. BMNR, by contrast, now trades at a slight discount to NAV — roughly 0.96×.
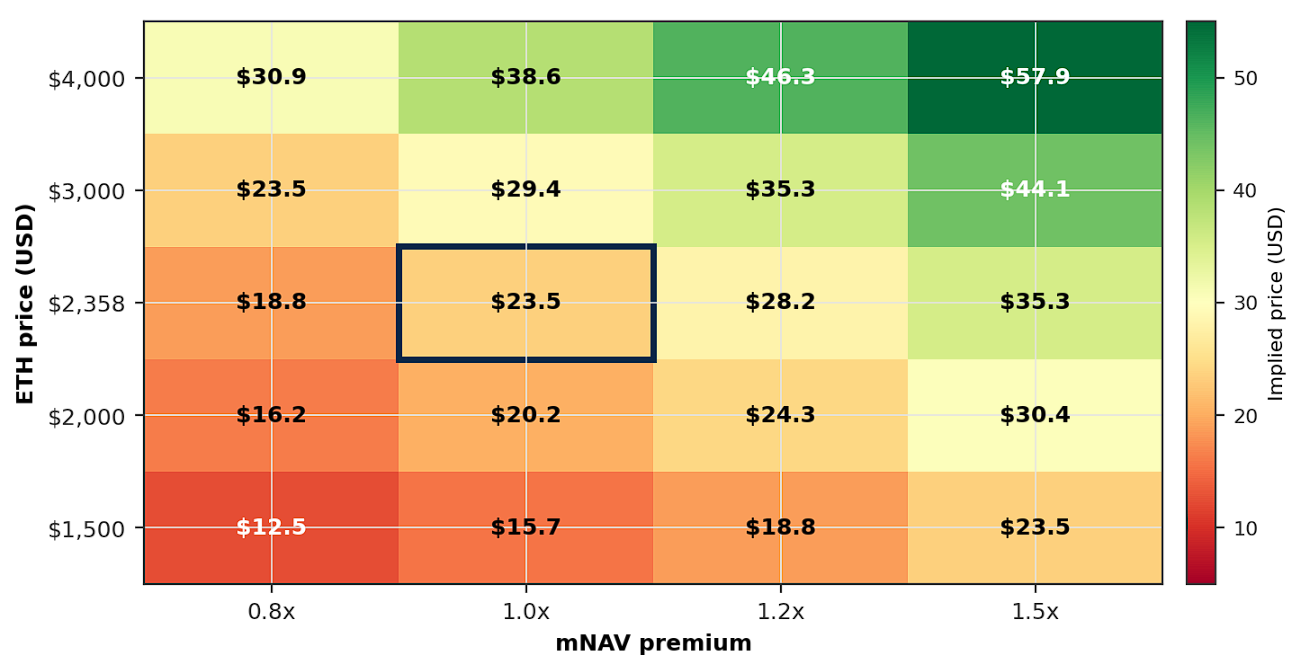
The highlighted cell is today’s trading zone — ETH ~$2,358, mNAV ~0.96×. Green cells are the bull case (up-right); red cells are the bear case (down-left).
That discount is not just a valuation curiosity. It is a structural problem. BMNR’s entire accumulation strategy depends on issuing shares at a premium to NAV — because only then does each new share buy more ETH per existing share than it dilutes. At a discount, every share issuance destroys per-share ETH value rather than creating it. The capital-markets channel that powered the 2025 accumulation strategy is now closed.
MSTR has a structural advantage here that BMNR lacks: a $8.3 billion stack of convertible notes and preferred shares that can be issued across mNAV regimes because the holders are underwriting fixed income, not NAV exposure. BMNR has no equivalent. It is entirely equity-funded and entirely procyclical.
There is a credible bull case that BMNR should eventually trade at a premium to MSTR — ETH generates a native staking yield that BTC does not, Ethereum’s programmability supports a larger long-term addressable market, and MAVAN if scaled provides operating-business value that MSTR’s enterprise software segment has never delivered. We take these arguments seriously. But three things make a persistent premium unlikely in the near term: ETH’s regulatory status on staking is contested while BTC’s commodity classification is settled; ETH is inflationary while BTC has a fixed supply; and BMNR’s compensation structure — discussed below — incentivises the wrong thing.
The compensation problem
In December 2025, BMNR put a compensation plan to shareholders for executive chairman Thomas Lee. It passed with 81% of votes. The plan is worth understanding in detail.
Structure of the compensation plan:
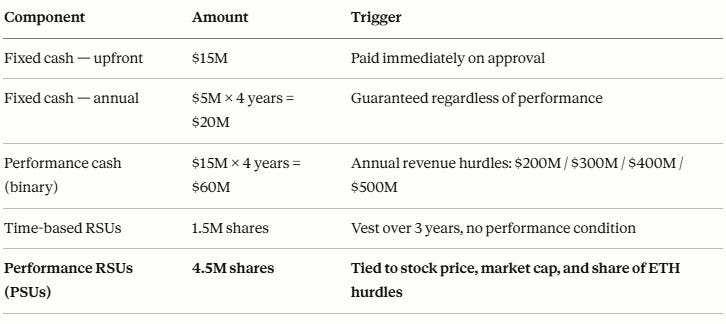
The plan totals up to $95M in cash and 6M shares over five years. That is not the problem. The problem is what it measures.
The cash revenue hurdles are met primarily through staking income, which scales linearly with total ETH held, ETH price, and network yield. None of those variables measure per-share value creation. Two of the three can be boosted simply by issuing more shares and buying more ETH with the proceeds.
More specifically: the PSU hurdles reference “share of ETH” — meaning the percentage of total ETH supply owned by BMNR, not ETH per BMNR share. A strategic dilution that takes the company from 4% to 5% of ETH supply by issuing shares at or below NAV would increase Tom Lee’s performance compensation while simultaneously reducing the ETH backing per share held by every other investor. That is a textbook principal-agent misalignment, and it is built into the structure of the plan.
The binary bonus structure amplifies this. There is no partial payout — Lee either hits the revenue hurdle or gets zero for that year. This incentivises maximum leverage towards the target rather than moderated accumulation. The FY30 hurdle of $500M in revenue, at current staking yields, implies approximately 7.6 million ETH staked — well past the publicly-stated 5% target. The plan is structured to incentivise accumulation well past the objective management tells the market it is aiming for.
What the macro environment adds
ETH vs BTC log scale with BTC dominance overlay
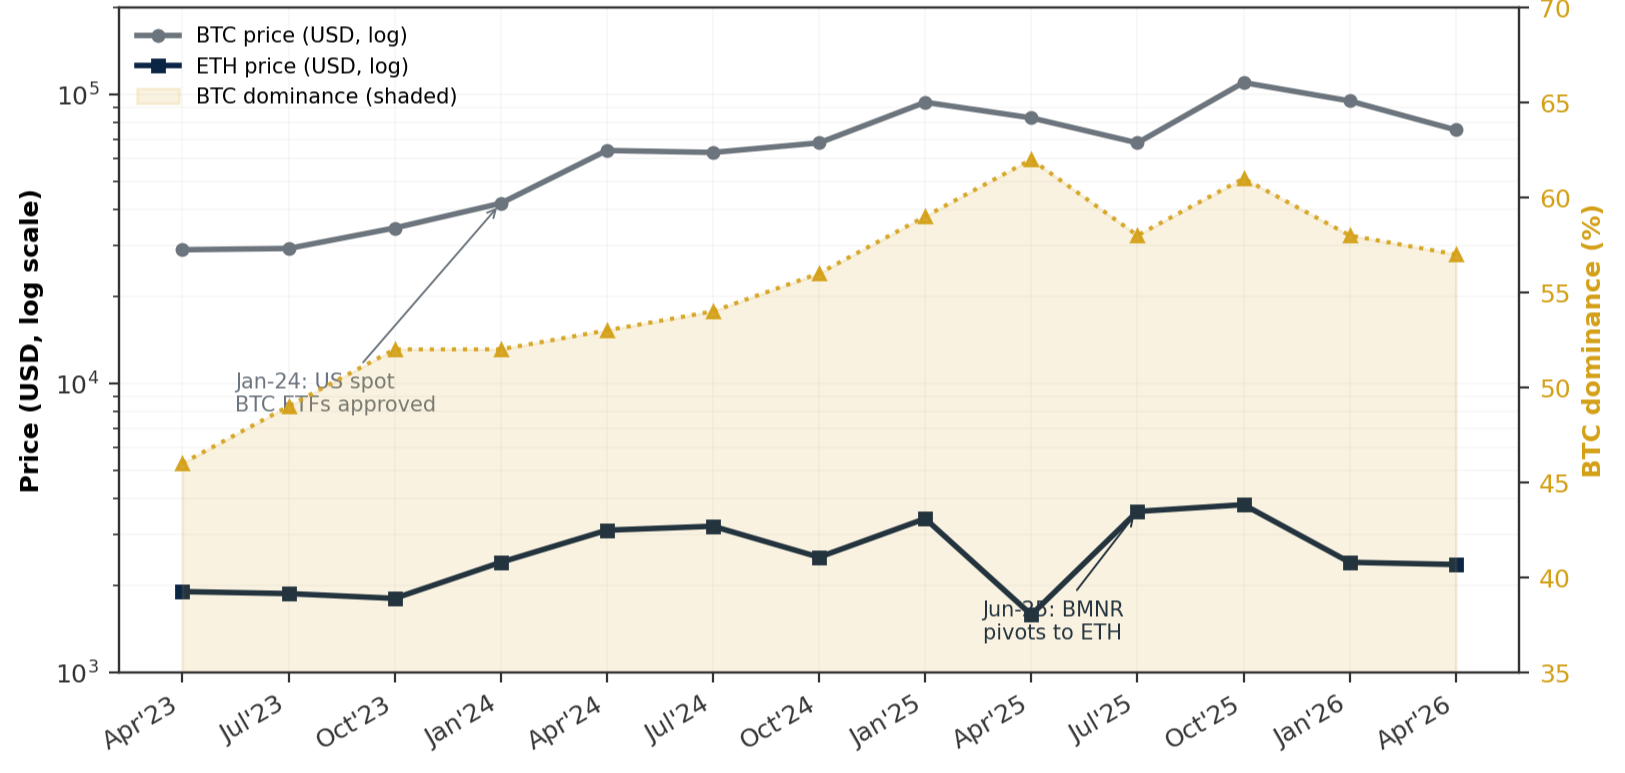
Bitcoin dominance has not dipped below 50% since September 2023 — the longest such period since early 2017. The ETF era has created a structural institutional preference for BTC that ETH has not disrupted.
The investment case for BMNR is effectively a bet that ETH outperforms BTC over the medium term. That bet has lost money for three years. Bitcoin dominance — the share of total crypto market cap represented by BTC — has risen from 46% in April 2023 to 57% today, peaking at 65% in mid-2025. In prior crypto cycles, this metric would have fallen sharply by now as capital rotated into alternatives. That rotation — historically called “altseason” — has not materialised. The 2024 spot-BTC-ETF approval appears to have created a structural institutional preference for Bitcoin that is proving stickier than the prior cycle suggested.
The macro environment adds pressure. The US economy is in a late-cycle phase with persistent inflation, a Fed that has abandoned its rate-cut trajectory, and equity markets at stretched valuations that reduce the margin for disappointment in high-beta assets. Crypto correlates negatively with real yields and positively with dollar liquidity. Higher-for-longer is a structural headwind for ETH. And risk-off conditions compress the mNAV premium that BMNR needs to fund its accumulation — which, as discussed above, is already at zero.
The valuation conclusion
Pulling it together: at current ETH prices (~$2,358) and a 0.95× mNAV base assumption, BMNR’s probability-weighted fair value is approximately $18.10 per share — below the current price of $22.63. The bear case (ETH $1,500, mNAV 0.85×) implies a target price near $14.83. The bull case (ETH $3,000, mNAV 1.20×) implies $39.08 — but requires ETH strength, premium recovery, a positive regulatory catalyst, and governance improvement to move simultaneously, which is why we weight it at only 15%.
A more extreme stress scenario — mNAV compressing to 0.70× in a forced-seller or governance-event dynamic — would imply a share price near $12.20. This is not the base case, but it is within the range of outcomes seen in the digital asset treasury sector.
The bottom line
The investment case reduces to an asymmetry question. BMNR offers one source of potential upside beyond holding ETH directly: MAVAN’s staking platform. But it also layers on three distinct downside risks that ETH itself does not carry — regulatory action on staking, dilution under the 50 billion share authorisation, and a compensation structure that incentivises total-asset growth over per-share value. One upside lever against three downside levers is not a favourable trade.
Investors wanting ETH exposure have cleaner alternatives — spot ETH, the US spot ETH ETF complex, or direct on-chain staking. The marginal-buyer and executive-compensation issues are the two most under-priced elements of the BMNR case. Each alone justifies caution. Together they support a SELL recommendation with a 12-month price target of $18.10.
Hans Jordan Hartanto — April 2026. This analysis was produced as part of a university equity research module. All figures reflect spot prices as of 17 April 2026: ETH $2,358, BTC $75,400. Not investment advice.